Market overview and structural significance of the Automotive Valves Market
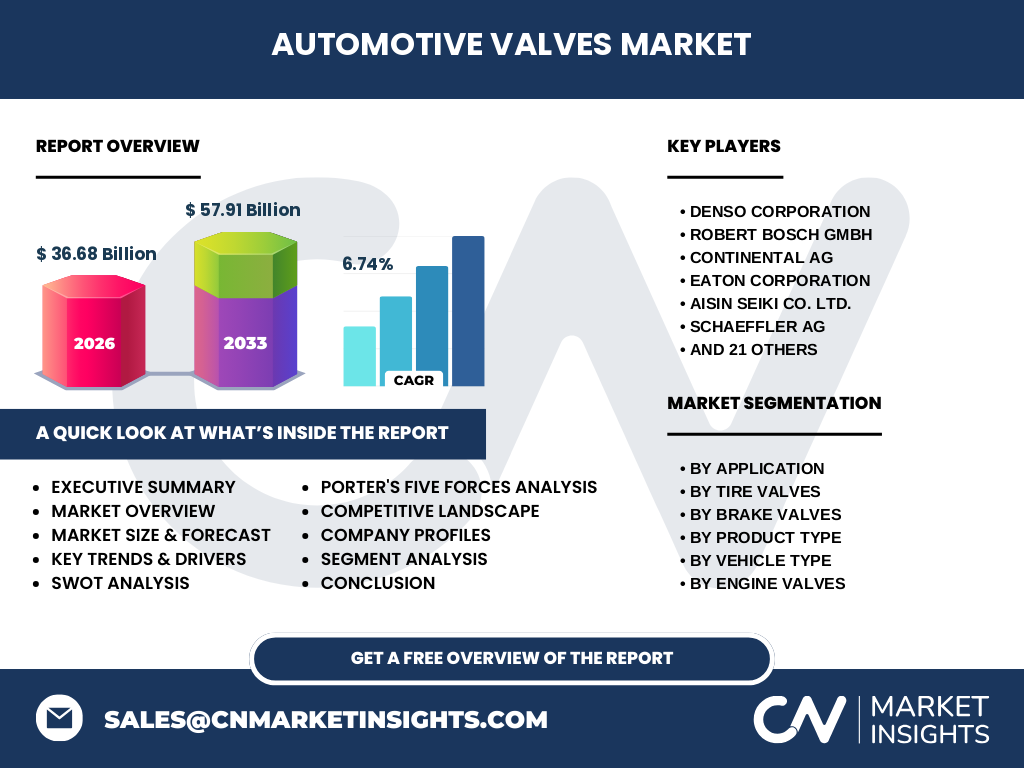
Our analysis indicates that the Automotive Valves Market encompasses critical fluid and gas control components across engine, brake, and thermal management systems. Valued at $36.68 Billion in 2026, this sector dictates powertrain efficiency, emissions compliance, and vehicle safety. Raw materials like forged steel, aerospace-grade aluminum, and specialized elastomers form the baseline of these high-precision fluid regulators.
What are the core market drivers, restraints, and opportunities shaping the Automotive Valves Market?
Stringent Euro 7 and EPA emissions mandates act as primary drivers, forcing adoption of advanced Electronic EGR Valves and Electronic Thermostat Valves. Conversely, raw material price volatility for stainless steel and silicon chips restrains margin expansion. Opportunities abound in thermal management for battery electric vehicles, particularly via high-performance expansion and solenoid valves.
Emerging trends and technological transformations in the Automotive Valves Market
The electrification wave accelerates demand for specialized thermal control architectures, pivoting production away from mechanical engine parts toward Normally Closed Solenoid Valves and advanced coolant regulators. Tier-1 suppliers increasingly integrate sensors into tire pressure monitoring system valves to feed predictive maintenance algorithms for commercial fleets.
How did the COVID-19 pandemic impact the Automotive Valves Market and dictate recovery?
Pandemic-induced semiconductor shortages and port congestion at major logistics hubs temporarily paralyzed automotive assembly lines globally. Recovery was anchored by strategic inventory buffers and localized sourcing. The crisis forced manufacturers to fast-track digital twin simulations for valve design, mitigating future supply chain disruptions.
Competitive benchmarking and strategic dynamics in the Automotive Valves Market
The landscape features high market concentration among established engineered-component titans. Firms like Denso Corporation and Robert Bosch GmbH dominate through proprietary fuel injector and powertrain valve innovations, while Eaton Corporation and BorgWarner Inc. focus on emissions and forced-induction valvetrain architectures to capture OEM contracts.
Executive summary of key findings in the Automotive Valves Market report
Our research underscores a robust expansion trajectory, projecting the market to reach $57.91 Billion by 2033 from its 2026 baseline. Propelled by a steady 6.74% CAGR, growth is heavily concentrated in sophisticated electro-mechanical systems across passenger cars and light commercial vehicles operating in tightly regulated urban zones.
Long-term market forecast and valuation trajectory through 2033
Based on our econometric modeling, the valuation will scale aggressively from $36.68 Billion in 2026 to $57.91 Billion by 2033, maintaining a consistent 6.74% CAGR. This upward vector is sustained by rising global vehicle electrification rates and mandatory safety legislations requiring advanced anti-lock braking infrastructure.
Segmentation analysis across applications, product types, and vehicle classes
The ecosystem is bifurcated by application (Engine, HVAC, Brake Systems), product type (Engine Valves, Solenoid Valves, Tire Valves, AT Control Valves), and propulsion. Passenger Cars represent the largest volume consumer, while electric vehicle platforms rapidly scale demand for specialized coolant expansion and pressure control components.
Regional market distribution and macroeconomic performance metrics
Geographic performance reflects local regulatory stringency and manufacturing footprints. The Asia-Pacific region dominates volume due to high automotive production clustering in China, Japan, and South Korea, whereas North America and Europe prioritize high-margin electronic thermostat and advanced exhaust gas recirculation valve upgrades.
In-depth regional review of key manufacturing and consumption hubs
North American demand relies heavily on light commercial truck production and strict NHTSA fuel economy rules, boosting fuel injector adoption. Meanwhile, European markets enforce aggressive carbon reduction targets, compelling automakers to integrate precision electronic EGR and thermal management valves across all internal combustion and hybrid architectures.
Strategic positioning of leading enterprise participants
Industry leaders maintain competitive moats through vertical integration and continuous R&D investment. Continental AG and Aisin Seiki Co. Ltd. focus on integrated braking valves, whereas Schaeffler AG and Mahle Group leverage deep metallurgical expertise to dominate mechanical and electronic valvetrain components for global OEMs.
Porter's Five Forces analysis of competitive intensity
Bargaining power of buyers remains moderate-to-high, as major global automakers dictate strict pricing terms to tier-1 suppliers. Threat of substitutes is low for core engine valves but rises for thermal components in EVs. Rivalry is fierce among incumbent giants holding patented actuation technologies and extensive global manufacturing footprints.
SWOT analysis of the global sector
Strengths lie in high switching costs and proprietary actuation designs. Weaknesses include high sensitivity to raw material input costs like nickel and chrome. Opportunities thrive in electric vehicle thermal management integration, while regulatory shifts and geopolitical trade tariffs represent notable external threats.
Value chain analysis from raw metallurgy to end-user integration
The value flow originates with specialty alloy producers supplying raw bar stock for forging. Tier-1 manufacturers machine, assemble, and test complex assemblies like Shift Control Valves before shipping to Tier-2 system integrators or directly to OEM assembly lines situated near major ports.
High-potential investment insights and strategic recommendations
Investors should target niche innovators specializing in thermal management for electric powertrains and electronic actuation systems. Companies partnering directly with battery cell manufacturers to supply specialized coolant control valves exhibit the highest upside potential for margin expansion.
Conclusion and critical takeaways for industry stakeholders
The transition toward electronic and software-defined valvetrain architectures defines the future of this sector. With a projected 6.74% CAGR leading to $57.91 Billion by 2033, long-term success requires strategic pivoting toward EV-compatible thermal and pressure regulation technologies.
Research methodology underpinning our baseline estimates and forecasts
Our findings are triangulated through extensive primary interviews with C-level executives at tier-1 suppliers, cross-referenced with customs trade registry data, and calibrated against macroeconomic indicators from international automotive federations to ensure absolute analytical integrity.
Scope of the report, coverage parameters, and analytical boundaries
This report covers global production, consumption, and technological evolution across nine distinct product categories and four major vehicle classes from 2026 to 2033. Aftermarket replacement channels and OEM factory-fit installations are fully factored into our comprehensive market sizing metrics.
Recent industry developments, strategic partnerships, and product launches
Recent market activity highlights aggressive joint ventures focused on thermal module integration. Leading participants have unveiled next-generation ceramic-coated valves designed to withstand extreme combustion pressures, alongside smart solenoid units equipped with onboard diagnostics to comply with emerging environmental monitoring standards.